
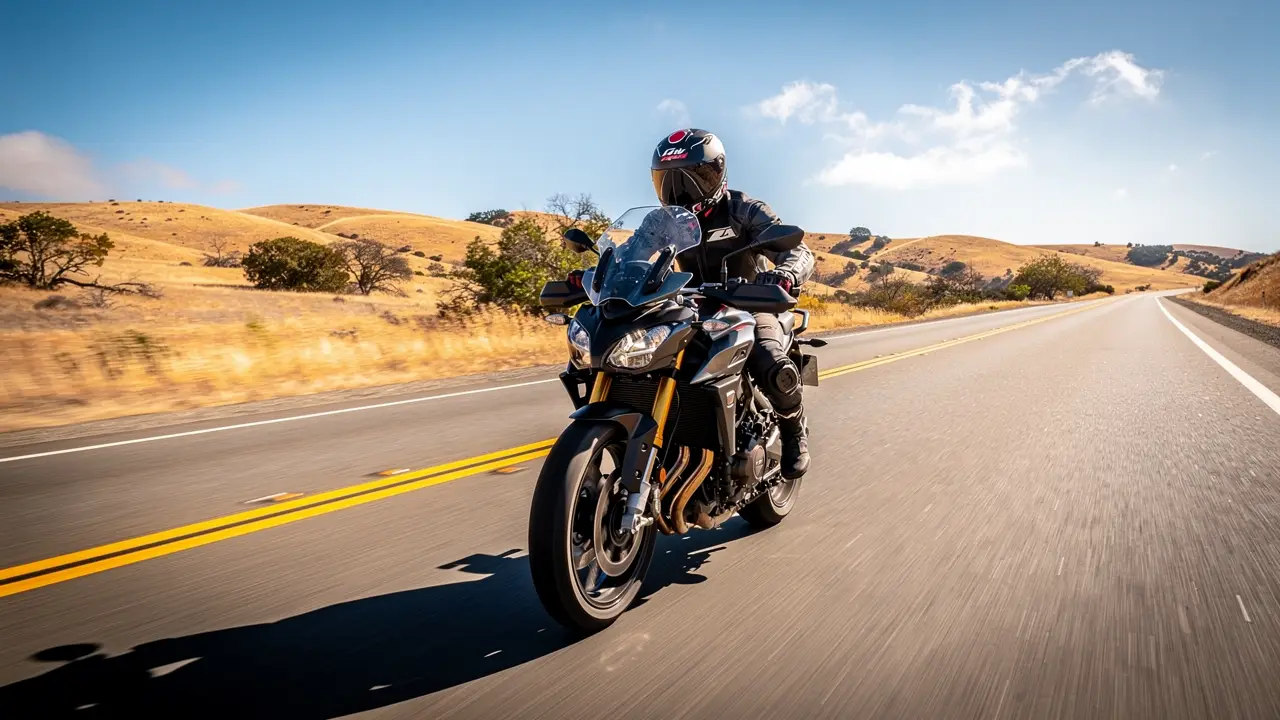
Motorcycle InsuranceBuilt for Riders
From Harleys to Vespas, sport bikes to ATVs - we cover every kind of California rider. Real quotes in 2 minutes, same-day coverage available.
Motorcycle Insurance
Liability for any bike, plus the coverage you choose
Rates are estimates, not guaranteed, and vary by driver, vehicle, and carrier underwriting.
Quick answer
California requires the same minimum liability on a motorcycle as on a car — 30/60/15: $30,000 for one person’s injuries, $60,000 per accident, $15,000 for property damage (Vehicle Code section 16430) — and you must be able to show proof when asked. Collision, comprehensive, uninsured motorist and custom-parts coverage are the choices on top. Auto World compares several motorcycle insurers for sport bikes, cruisers, touring bikes, scooters and ATVs, including riders with a DUI or an SR-22, and coverage can often start the same day.
We Cover Every Type of Ride
From daily commuters to weekend warriors - if it has two wheels (or four for ATVs), we\'ve got you covered.

Motorcycles
Cruisers, sport bikes, touring, adventure - all makes and models
Popular brands: Harley-Davidson, Honda, Yamaha, Kawasaki, BMW, Ducati
Scooters & Mopeds
From 50cc city scooters to powerful maxi-scooters
Popular brands: Vespa, Honda PCX, Yamaha XMAX, Genuine Buddy

ATVs & UTVs
Off-road vehicles for work or recreation
Popular brands: Polaris, Can-Am, Honda, Yamaha, Arctic Cat
Built for California Riders
We understand what makes riding in California unique
Year-Round Riding Weather
California's amazing climate means you ride more. We understand the unique needs of riders who log serious miles.
Lane Splitting Is Defined in the Vehicle Code
California defines lane splitting in Vehicle Code section 21658.1 and lets the CHP publish safety guidelines for it. Ride it the way those guidelines describe — a claim is judged on what happened, not on the fact that splitting is allowed.
Diverse Terrain
From PCH coastal rides to mountain twisties - we cover you wherever California's roads take you.
Coverage Options & Pricing
Customize your coverage to fit your ride and your budget
Liability Coverage
Required by California law. Covers injuries and property damage you cause to others while riding.
Collision Coverage
Pays to repair or replace your bike after an accident, regardless of fault.
Comprehensive Coverage
Covers theft, vandalism, fire, weather damage - everything except collisions.
Uninsured Motorist
Protects you if hit by an uninsured driver - critical in California.
Medical Payments
Covers your medical bills after an accident, regardless of fault.
Custom Parts & Equipment
Protects aftermarket parts, chrome, custom paint, and accessories.
Motorcycle insurance after a DUI or with an SR-22 in California
A DUI in California affects your whole driving privilege, not just the vehicle you were in — so a DUI in a car follows you onto a bike, and a DUI on a bike follows you into a car. If the DMV requires an SR-22, it can be attached to a motorcycle policy; if you do not own a bike or car, a non-owner SR-22 satisfies the filing.
- ✓SR-22 on a motorcycle policy: we file it electronically with the California DMV the same business day the policy is bound; the DMV may release the filing after three years from the date the proof was required (Vehicle Code section 16480).
- ✓What it costs: the filing itself is a small fee; the DUI is what moves the premium. Post-DUI motorcycle rates vary widely between carriers, which is why we quote several specialty carriers rather than one.
- ✓How long it follows you: a DUI stays on a California driving record for 10 years; how heavily each insurer weighs it in the later years varies by insurance company.
- ✓No bike yet? A non-owner SR-22 reinstates the license first; we move the filing to the bike policy the day you buy one, with no gap.
Full detail on the DUI rules is on DUI insurance in California and SR-22 insurance in California. Comparing carriers before you buy? Read our best motorcycle insurance in California (2026) guide, then come back here to bind.
California riders’ guides
Plain answers to what riders ask us before and after they buy — each one cites the Vehicle Code section behind it.
Motorcycle Insurance FAQs
Everything you need to know about insuring your ride in California
What is the minimum motorcycle insurance required in California?
How much does motorcycle insurance cost in California?
Do I need insurance for a scooter or moped in California?
Is ATV insurance required in California?
Can I get motorcycle insurance with a DUI or accidents?
Does motorcycle insurance cover my custom parts?
What discounts are available for motorcycle insurance?
Where this comes from
- California Vehicle Code section 16430
Minimum liability: $30,000 per person, $60,000 per accident for injuries, $15,000 for property damage.
- California Vehicle Code section 16028
You must show evidence of financial responsibility when asked; a phone display is allowed.
- California Vehicle Code section 38020
An off-highway vehicle that is not street-registered may not be operated or left standing without OHV identification, except as the division provides.
- California Vehicle Code section 21658.1
Defines lane splitting and lets the CHP develop educational safety guidelines for it.
- California Vehicle Code section 16480
The DMV may cancel a certificate of insurance or waive the filing requirement after three years from the date the proof was required.
This page explains California rules in plain language. It is general information, not legal advice, and it does not describe any particular insurance company’s procedures. The terms of your own policy and any notice you have received control your situation.
Ready to Ride with Confidence?
Sport bike, cruiser, scooter or ATV — a licensed California broker compares several motorcycle insurers for you. Get your personalized quote in just 2 minutes.
✓ All bike types covered ✓ No SSN required ✓ Same-day coverage